Board Candidates 2026

NAGGL Board of Directors Election – Terms Beginning January 2027
General Information
The following questions were asked of each nominee in order to determine their stance on current SBA policies and their ideas for setting priorities for the association. Please review each candidate’s responses to help determine whose priorities for the 7(a) program and NAGGL most closely match your own.
- If you could make one change in SBA’s 7(a) loan program requirements, what would you change and why?
- What are the main weaknesses that you believe the SBA should focus on to improve the performance of the 7(a) loan program?
- What would you recommend that NAGGL set as its top priority in its capacity as a representative of lenders and others involved in SBA 7(a) lending?
Lending Institutions (5 Seats Open, 10 Nominees)
Kale Gaston
Head of Small Business Lending, Happen Bank
Scott Gillanders
SVP Director of Credit and Operations, Beacon Bank & Trust
Diane Heyden
Sr. Vice President\/Director of SBA Lending, West Coast Community Bank
About Kale
Kale Gaston has 40+ years of commercial lending and SBA experience. He has led teams at community banks, regional banks and large national banks throughout his career.
He began his career working at an SBA Certified Development Company (CDC) in Kansas and then was the Executive Director of a CDC in Colorado. From there he continued as the head of SBA programs at TD Bank and Bank of America, as well as a SBLC (non-bank lender).
He is currently the Head of Small Business Lending for Happen Bank, which is one of the few fintechs that has acquired a commercial bank and has a SBA lending operation.
Growing up and working in a family-owned small business and seeing the impact it had on the community created his passion for small business and the SBA lending programs.
He is a member of the Board of Directors and Executive Committee for NAGGL as well as on its Public Policy/Large Lender Committee. He is also a member of the Executive Committee and Vice Chairman of the Board of Directors for Pursuit Certified Development Company and a former Board Director for the National Association of Certified Development Companies (NADCO).
Answers to Questions
- We need to continue to work with SBA to make SBA lending easier and less costly. Since doing my first SBA loan a little more than 40 years ago, it seems that doing loans 40 years ago was easier. We have to make sure the 7a program has long term viability, and we have to protect the integrity of the program. We can do that and not have to layer requirements on top of requirements to make sure lenders are doing what they are supposed to be doing. The program really should be on a merit basis. If you are doing the right loans the right way, then you would be rewarded for that. Lender on-going fees and guaranty fees really should be based on lender performance. I would love to see us work with SBA to focus on ease of implementation and cost effectiveness of the program.
- I agree with most of the changes made recently to the SOP. SBA needs to continue to improve ways they can look into the future and see where the program is succeeding and where it is not working as well. Historically, SBA has been slow to react to problems in the program and make the appropriate changes to protect the long-term viability of the program. New technologies should help SBA be more proactive and work more in partnership with lenders to not only improve portfolio performance but increase the number of lenders using the program as well.
- Having been on the Board of Directors for several terms I believe in the mission of NAGGL and believe that NAGGL is going a good job of representing SBA lenders across the board. I would love to see NAGGL do more outreach to lenders and provide opportunities for lenders to talk about things on their mind on a more frequent basis. All of the conferences and the new member meet ups are doing a good job. I’d love to see us do more frequent Zoom\/Teams calls with lenders to discuss things on their mind at that point in time. With the cutbacks at SBA there are no longer good local lender reps and many lenders relied on them for support. I feel that NAGGL can help fill that gap. NAGGL adds value and I will continue to work hard to make sure lenders see that value.
About Scott
A native Californian, Scott started his career in the late 1980s at Wells Fargo in San Francisco. Based in Philadelphia since 2000, Scott has held various credit management roles where he is currently Sr. Vice President, Credit & Operations Director for Government Guaranteed Lending at Beacon Bank & Trust, a $24bn bank headquartered in Boston. He oversees all aspects of the credit, closing, construction disbursement, servicing, and collection efforts of the bank’s SBA department. Beacon is consistently ranked as a top twenty-five lender of US Small Business Administration 7a loans and has over a $1bn portfolio. Scott holds a BS Degree from Drexel University with a minor in Architecture.
Answers to Questions
- Our industry should constantly be thinking about how we can all be good stewards of the program in being proponents for thoughtful evolution of our program. I would advocate for more required technical assistance from partners such as the SBDC and SBA where staffing would be available to have mandatory counseling for transactions over $3MM dollars involving change of ownership where the prior background of the buyer is not aligned with the NAICS code to be purchased. This could be web based and be structured as an affirmation and pledge by applicants that they are engaged as owner\/users of the business. With the rise in silent partners, we must continue to be vigilant that credit is truly not available elsewhere and we are being good stewards of the taxpayer program.
- I believe additional risk based rewards for Lenders with quality metrics should be proposed. If SBA were to provide lower lender fees for those Lenders with scores trending towards improvement this would encourage more prudent behavior; additionally there is still weakness in the program in the change of ownership rules that should be reviewed to promote sound transfer of ownership. Keeping equity in the balance sheet of newco remains a challenge
- A responsible increase to the program limits with the commensurate middle market covenants to permit larger transactions that can benefit the economy while not risking the portfolio to further harm from non prudent lending.
About Diane
Diane Heyden brings over 30 years of experience in the financial services industry, with a specialized focus on SBA lending. Throughout her career, she has led nationwide SBA sales initiatives, launched a successful SBA loan origination program, and built high-performing teams of Business Development Officers. Her leadership has consistently driven operational efficiency and strategic growth within the SBA departments she has overseen.
Currently, Heyden serves as the head of SBA Lending at West Coast Community Bank, where she leads efforts across the bank’s four-county service area: Monterey, San Luis Obispo, Santa Clara, and Santa Cruz.
Her commitment to community service includes board membership with the Huntington Beach Educational Foundation and serving as Chair of the Huntington Beach 4th of July Board, a role appointed by the City Council.
Heyden is a graduate of the Pacific Coast Banking School and an active member of the National Association of Government Guaranteed Lenders (NAGGL). She notably served as Chair of NAGGL’s Small Bank West Committee for five consecutive years.
Answers to Questions
- Create a Fast-Track Program for High-Performing Lenders\r\nWhy: Lenders with a strong track record of low default rates and compliance could benefit from expedited processing or reduced documentation requirements. This would reward responsible lending and improve efficiency.
- Expand Use of Technology for Monitoring and Compliance\r\nWhy: Implementing real-time data analytics and digital reporting tools could help the SBA monitor loan performance more proactively, identify early warning signs, and reduce fraud or misuse of funds.\r\nIncrease Transparency in Loan Denials\r\nWhy: Many small businesses are denied SBA loans without clear explanations. Requiring lenders to provide standardized, detailed feedback could help borrowers improve their applications and reapply successfully
- Advocating for Balanced Policy Changes\r\nNAGGL should ensure that policy shifts—like the reinstatement of guaranty fees and stricter credit criteria—don’t disproportionately impact small or underserved borrowers. The association can:\r\n•\tPush for tiered or flexible fee structures.\r\n•\tRecommend alternative credit evaluation tools for thin-file borrowers.\r\n•\tAdvocate for continued modernization of SBA systems and processes.
James "Jim" Kahler
EVP - SBA Director of Operations, Gulf Coast Small Business Lending, a Division of Gulf Coast Bank & Trust Company
Carly Lovenguth
Director of SBA Operations, Busey Bank
Richard "Rich" Mason
Senior Vice President- SBA Underwriting and Operations Manager, Fulton Bank, N.A.
About Jim
Jim Kahler has worked in SBA lending since 1994, bringing more than 30 years of experience across all aspects of the industry. He currently serves as EVP–SBA Director of Operations for Gulf Coast Small Business Lending, a division of Gulf Coast Bank & Trust Company. Jim earned an MBA in Marketing and a BBA in Management and Entrepreneurship from Baylor University. He is a founding member of the North Texas Association of Government Guaranteed Lenders (NTAGGL), Jim served as its President from 2014–2015 and Chairman from 2016–2017. He has also held several other officer and committee leadership positions. Jim currently chairs the NAGGL Region 6 Lenders Committee, serves on the NAGGL Small Lender Committee, and mentors participants in NAGGL’s Future Lending (FLL) Leaders program. He is also a member of the ProSight (RMA) eMentor Advisory Board and the North Texas SBDC Advisory Board. An active industry educator, Jim regularly speaks to the SBA THRIVE (formerly e200 & Emerging Leaders Initiative) program. He has moderated and taught numerous SBA lending courses and presented at NAGGL conference breakout sessions, the Mid-America Lenders Conference, America West Conference, Future Branches Conference and Federal Reserve Bank forums.
Answers to Questions
- To me, an important and vital program requirement should be clear and consistently applied total exposure limit for individuals who own or control multiple businesses financed through the SBA programs.
While each separate business may qualify independently, borrowing through multiple ownership structures can create problematic concentration and allow one individual to receive total lending support that may be inconsistent with the program’s broader purpose. A reasonable total limit—supported by specific, transparent rules addressing ownership, control and guaranties—would help ensure that program resources remain available to provide a much broader access to capital for small businesses.
These standards should be carefully structured so they do not restrict legitimate serial entrepreneurs or their ability to responsibly expand. The objective should be to encourage growth but still establish appropriate boundaries. The standards should reduce opportunities to circumvent the rules of the program while still protecting the spirit of the program. This will protect the long-term integrity and sustainability of the 7(a) program while allowing the necessary access to capital.
- One of the primary areas SBA should address is the ambiguity that remains within certain sections of the SOP. The SOP provides a strong foundation for the 7(a) program, some requirements allow for interpretations that vary significantly among lenders, reviewers, and SBA personnel.
SBA should provide clear standards in the program’s areas of greatest concern. To further enhance this, timely issuance and consistent interpretations of any ambiguities will help. With the continued enhancement of AI, maintaining a centralized, searchable source of formal guidance will provide for rapid and consistent implementation. The increased clarity will promote sound lending practices, reduce uncertainty, and help prevent program requirements from being stretched beyond their intended purpose.
The rapid, clear guidance should be enhanced by continued risk-based oversight that will isolate technical errors from practices that create meaningful credit, compliance, or program-integrity concerns. This will allow responsible lenders to compete on a level playing field while addressing practices of some lenders that could undermine the program.
Clear, consistently administered program will improve loan performance, support zero-subsidy objectives, and preserve reliable access to capital for deserving small businesses.
- NAGGL’s top priority should be preserving the long-term strength, accessibility, and affordability of the 7(a) program by continuing to serve as an effective bridge between SBA and the lending community.
This includes advocating for clear and workable policies, reasonable implementation timelines, consistent interpretation of program requirements, and modernization that improves efficiency without weakening program integrity. NAGGL should also continue providing lenders with high-quality education, practical guidance, and meaningful opportunities to communicate how policy changes impact borrowers and program delivery.
Whenever possible, NAGGL should use member experience and reliable program data to demonstrate the operational, financial, and borrower-level effects of proposed changes. This allows the association to be both a strong advocate for its members and a constructive partner to SBA.
A stable and consistently administered program encourages lender participation, protects its zero-subsidy objective, and ensures that small businesses continue to have dependable access to capital.
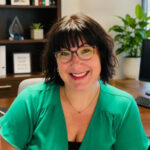
About Carly
Carly Lovenguth is the Director of SBA Operations at Busey Bank, where she has built a distinguished banking career spanning more than 23 years. With 18 years of commercial lending experience, she has specialized in Small Business Administration (SBA) lending since 2017, developing extensive expertise in SBA operations, compliance, servicing, risk management, and portfolio administration.
Throughout her career, Carly has focused on helping deliver SBA financing while balancing sound credit practices, operational excellence, and regulatory compliance. She is passionate about supporting small business growth and strengthening SBA lending programs to better serve borrowers and communities.
Carly is an active member of the National Association of Government Guaranteed Lenders (NAGGL), serving on both the Region V Committee and the Small Lender Committee. She is also a graduate of NAGGL’s Future Leading Lenders Program, which prepares emerging industry leaders to advance and advocate for the SBA lending community.
Drawing upon her extensive operational and lending experience, Carly is a strong advocate for practical, risk-based approaches to SBA lending and is committed to advancing initiatives that improve program accessibility, efficiency, and long-term success for lenders and small business borrowers alike.
Answers to Questions
- If I could make one change to the SBA’s 7(a) loan program, it would be to place greater emphasis on whether a lender made a prudent and well-supported credit decision rather than on whether every procedural requirement was interpreted exactly as intended by the SBA.
I am not suggesting that compliance standards should be relaxed or that lenders should not be held accountable for following SBA requirements. However, when a lender has thoroughly underwritten a loan, properly documented its analysis, and can demonstrate that it made a sound lending decision, minor procedural or documentation deficiencies that had no impact on the performance of the loan should not result in a guaranty repair or denial.
The SBA program is most effective when it balances compliance with sound credit judgment. A greater focus on the quality of the underwriting decision and the lender’s overall risk management approach would encourage prudent lending while maintaining the integrity of the program. In my view, the SBA has increasingly shifted toward technical compliance, and restoring a stronger emphasis on credit quality and materiality would benefit both lenders and the long-term success of the 7(a) program.
- One weakness the SBA should focus on is the timing and accessibility of portfolio risk management data available through the Lender Portal. While the portal provides valuable tools and insights that help lenders identify industries, business segments, and trends experiencing increased stress, much of this information becomes available only after a loan has been originated and closed. Providing lenders with access to these tools and analytics during the underwriting process would enable more informed credit decisions, strengthen portfolio quality, and enhance risk management. Earlier access to this data could help lenders proactively identify emerging risks while continuing to support qualified small business borrowers.
- One of NAGGL’s top priorities should be increasing education and awareness among bank and lending institution executive leadership about the unique nature of SBA lending. Too often, decision-makers view SBA lending through the same lens as conventional lending and fail to recognize the additional compliance requirements, operational complexities, and customer needs that make the program different.
As a result, many institutions establish SBA departments that are structured and managed like conventional lending departments rather than specialized SBA operations. This can lead to unrealistic performance expectations, inadequate staffing and training, poor customer experiences, and ultimately unsuccessful SBA programs.
By helping executive leaders better understand the SBA lending environment and the resources required to support it effectively, NAGGL can promote stronger SBA programs that are better positioned to serve small business borrowers, maintain compliance, and achieve long-term success.
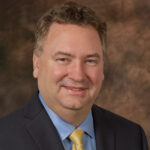
About Rich
Richard Mason is a Senior Vice President and SBA Underwriting & Operations Manager at Fulton Bank, N.A., a $34.6 billion commercial bank with a nationwide SBA lending platform. He serves as the bank’s subject matter expert on SBA lending programs, providing guidance and oversight on eligibility, compliance, loan structuring, underwriting, approvals, servicing, and life-of-loan requirements across a broad SBA portfolio.
With more than 28 years of experience in government-guaranteed lending, Rich has dedicated his career to helping entrepreneurs and small businesses access capital for acquisitions, ownership transitions, commercial real estate, construction, equipment purchases, working capital, export financing, franchise financing, startups, and business expansion. His expertise spans the full lifecycle of SBA lending and includes extensive experience with all SBA loan products supporting lenders in delivering compliant and effective financing solutions.
Rich currently serves as Chair of the National Association of Government Guaranteed Lenders (NAGGL) Region III Committee, a leadership role he had held for more than 15 years, where he works closely with lenders throughout the region to promote education, collaboration, and industry best practices. A frequent speaker and panelist at industry conferences, he is recognized for his expertise in SBA eligibility, compliance, underwriting, and risk management.
Rich earned a Bachelor of Science degree from La Salle University and holds the NAGGL Advanced Lender Diploma. He is passionate about strengthening the SBA lending industry and advancing NAGGL’s mission in support of small business lenders nationwide.
Answers to Questions
- If I could make one meaningful change to the SBA lending program, I would expand and modernize the SBA’s small loan offering through streamlined processing, enhanced credit guardrails, and SBA-hosted digital application technology.
Throughout my career, I have seen the critical role small-dollar financing plays in helping entrepreneurs start, acquire, and grow businesses. Yet loans in the $50,000 to $250,000 range are often the most difficult for lenders to originate because upfront origination costs, underwriting, documentation, compliance, and servicing requirements can approach those of much larger transactions.
I believe there is an opportunity for the SBA, lenders, and industry stakeholders to collaborate on a modernized small loan framework that balances prudent risk management with greater access to capital. While past models such as SBSS provided processing efficiencies, future solutions should leverage modern credit analytics, alternative data, and risk-based underwriting standards that support both portfolio performance and lender participation.
An SBA-hosted electronic application and processing platform could further reduce borrower friction, improve consistency, and lower origination costs. Most importantly, these enhancements would expand access to capital in underserved communities and help ensure that entrepreneurs seeking modest amounts of financing have a viable path to business ownership and growth.
- The SBA can strengthen the 7(a) loan program and attract more lenders by focusing on four key areas.
1. Simplify and Shorten the SOP. The SOP has become increasingly complex, making it more difficult and costly for lenders to originate and service SBA loans. Streamlining requirements and reducing unnecessary complexity would improve efficiency and consistency.
2. Reduce Lender Oversight Fees. Oversight and participation costs can discourage lender involvement, particularly among community banks and smaller institutions. Lower fees would improve program economics and encourage greater participation.
3. Improve Access to SBA Portfolio Data. Lenders would benefit from greater transparency regarding portfolio performance by industry, geography, and franchise brand. Enhanced access to data would support stronger underwriting, portfolio management, and risk assessment.
4. Expand Non-Delegated Processing. SBA should increase non-delegated processing capacity and encourage lenders to submit higher-risk or more complex transactions for SBA review. In some cases, lenders may decline viable loans because they are hesitant to assume the risk of approving unusual or policy-sensitive transactions under PLP authority. A more accessible and responsive non-delegated process would provide lenders with an alternative path to approval, allowing additonal creditworthy small businesses to obtain financing while maintaining prudent credit standards.
These changes would reduce complexity, improve lender participation, increase transparency, and expand access to capital for small businesses.
- I would recommend that NAGGL make increased legislative and regulatory advocacy a top priority by pursuing an increase in the SBA 7(a) loan cap to at least $7.5 million or, preferably, indexing the cap to inflation as a future strategy. The current $5 million limit has remained unchanged for more than 15 years despite substantial inflation, rising business acquisition valuations, increased construction costs, and greater working capital needs. A $5 million cap established in 2010 equates to approximately $7.5 million in today’s dollars, making a higher limit a logical modernization of the program.
While increasing the cap to $10 million would provide even greater support for business acquisitions, business growth, job creation, and economic development, any increase should be accompanied by appropriate credit standards and risk management safeguards to maintain portfolio quality.
NAGGL should also advocate for the complete decoupling of the SBA 7(a) and 504 loan program limits. Recent SBA policy changes effectively created an advantage for the 504 program by excluding existing 7(a) balances from the 504 cap while continuing to count 504 debt against the 7(a) cap. Congress should establish independent statutory loan limits for each program to place them on equal footing, increase access to capital, and allow lenders and borrowers to utilize both programs as intended without unintended restrictions.
Clarizza Paz
SBA Underwriter and Servicing Officer, American National Bank & Trust
Charles Rho
President, U.S. Bank
Lindsay Spitler
Vice President, SBA Program Manager, ChoiceOne Bank
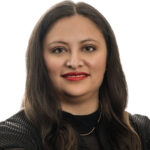
About Clarizza
Clarizza Paz, is an SBA banking professional with experience spanning underwriting, servicing, portfolio management, and government-guaranteed lending. She currently serves as SBA Underwriter & Servicing Officer with American National Bank & Trust, where she supports the bank’s SBA lending program through loan structuring, credit analysis, servicing and portfolio oversight.
Her experience includes SBA 7(a)and 504 lending and has provided her with a practical perspective on the complete life cycle of a government-guaranteed loan from initial eligibility and credit analysis through closing, servicing, and ongoing risk management.
Prior to her banking career, Clarizza served and retired from the U.S. Army as a Transportation and Logistics Officer, attaining the rank of Captain and served in Afghanistan. She holds an associate degree in Accounting, a bachelor’s degree in Management and an MBA.
Clarizza believes strong SBA programs require both disciplined risk management and practical implementation. She is passionate about strengthening communication between lenders and SBA, improving consistency in program administration and ensuring that responsible lenders have the tools and regulatory clarity necessary to expand access to capital while protecting the long-term integrity of the 7(a) program.
Answers to Questions
- If I could make one change to the SBA 7(a) program requirement, I would provide greater clarity regarding where mandatory SBA requirement ends, and prudent lender judgment begins. Delegated lenders are entrusted to make credit and eligibility decisions yet ambiguity can remain regarding whether certain provisions are mandatory requirements, prudent lending consideration, or recommended practices. This can lead to inconsistent interpretations among lenders and create uncertainty when loans move from origination through closing, servicing, liquidation, and ultimately guaranty purchase.
I’d encourage SBA to more clearly distinguish requirements that directly affect program eligibility or the guaranty from areas where lenders are expected to exercise and document prudent credit judgement. Where lender discretion is intended, the SOP should clearly state that discretion and the standard the lender is expected to meet.
- One of the greatest opportunities for improvement is consistency across the full life cycle of a 7(a) loan. Lenders need requirements that are clear not only at origination, but also through closing, servicing, liquidation, and guaranty purchase.
Policy changes and differing interpretations can create uncertainty about what constitutes prudent lender judgment versus a guaranty risk. SBA should continue improving the clarity and timeliness of its guidance while creating stronger feedback loops between origination, servicing, liquidation and program performance.
SBA also possesses substantial loan performance data that could help lenders make better credit decisions. Providing lenders with more meaningful anonymized information regarding defaults, recoveries, industries, transaction structures, and recurring deficiencies would allow the industry to identify emerging risks and strengthen underwriting before problems occur.
Finally, oversight should increasingly distinguish between isolated technical deficiencies and practices that create genuine credit, eligibility, or program integrity risk. A more risk focused approach would allow SBA and responsible lenders to direct resources toward the issues most likely to cause losses while maintain strong accountability for program compliance.
- NAGGL’s top priority should be to ensure that the practical experience of responsible SBA lenders is incorporated into policy development before changes become operational requirements. NAGGL is uniquely positioned to connect SBA and policymakers with professional working at every stage of the loan life cycle. That perspective is particularly valuable when evaluating whether a proposed requirement will meaningfully reduce risk, unintentionally restrict access to capital or create operational burdens without improving program performance.
I would encourage NAGGL to continue strengthening structured feedback between lenders, SBA leadership, and policymakers while using industry and loan performance data to support its advocacy. Policy discussions should include not only what a rule is intended to accomplish, but how it will function in underwriting, closing, servicing, liquidation, and examination.
The objective should be a 7(a) program that is sustainable, accessible, and accountable; one that protects taxpayer resources and program integrity while giving responsible lenders sufficiently clear and practical rules to serve small businesses effectively.
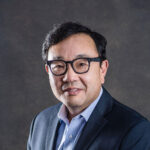
About Charles
Charles is an accomplished business development and corporate strategy executive with over 25 years of progressive leadership experience in building and implementing strategic plans in the commercial finance sector. Charles worked for General Electric’s Capital (GEC) business unit from 1997 to 2014. During his 17-year career with GEC, Charles launched several new business units, ran GE’s SBA secondary market group, and was part of the M&A team with GE’s corporate strategy unit. He closed over $11 billion in commercial real estate, M&A and leverage finance transactions. In 2012, Charles was 1 of only 24 leaders selected globally by GEC for their future leadership program. In 2014, Charles joined CBRE Capital Markets. During his time at CBRE, Charles founded the Asian American affinity group called CBRE Asia Pacific American Forum. He served as Founder & Chairman and appointed 9 regional leaders to lead CBRE APAF nationally.
Throughout his career, Charles’ passion was with small business lending, in particular with SBA lending where his commercial lending career began after graduating from college. In 2017, he returned to SBA lending by launching a new Small Business Lending Company, VelocitySBA, and growing the business to top 35 SBA 7a lender in the country.
Answers to Questions
- I would advocate to reinstitute borrower eligibility to US Citizens and LPR. Backbone of the American economy is driven by small businesses and historically lawful permanent residents have played a significant part in operating, managing and owning small businesses. SBA program should support all lawful residents.
- Robust loan performance data sharing and analytics with lenders to develop a safer lending program for borrower, lenders and the SBA. Leverage performance data to effectuate lending guidelines that better assess and manage risk for the 7a program.
- I believe data is the key to support the 7a lenders, especially with delinquency and default rates on the rise. I believe NAGGL should advocate for loan performance data and provide monthly updates to its membership. Performance data is difficult for many member lenders to 1) obtain and 2) analyze. I believe NAGGL can provide loan performance metrics based on industry, use of proceeds, term, geography, etc, on a monthly basis which can be leverage by its membership to lower the risk of new loan origination and ultimately enhance the 7a program for all.
About Lindsay
I am a commercial banking professional with more than 25 years of experience in SBA and commercial lending. Currently, I serve as Vice President and SBA Program Manager at ChoiceOne Bank, leading all aspects of the SBA 7(a) and 504 lending programs, including origination, underwriting, compliance, and portfolio management.
Prior to ChoiceOne, I held key roles at Bank of America, Fifth Third Bank, and Mercantile Bank of Michigan, building broad expertise in credit underwriting, portfolio management, and SBA business development.
I hold a Master of Business Administration from Western Michigan University and a Bachelor of Science in Business Administration from Central Michigan University. Additionally, I earned the NAGGL Lender Diploma and am currently attending the Graduate School of Banking at the University of Wisconsin–Madison.
Dedicated to community engagement, I serve on the board of the Lions & Rabbits Center for the Arts and have long supported small business development through education and volunteerism.
I live in Grand Rapids, Michigan, with my husband, Brent, and our three children.
Answers to Questions
- If I could make one change to the SBA 7(a) program, it would be to improve consistency and simplify some of the requirements around loan processing and eligibility. The program works best when lenders have a clear understanding of expectations and can provide timely decisions for small business owners. Over the years, additional requirements and differing interpretations of guidance have added complexity for both lenders and borrowers. I believe SBA can maintain strong credit standards while providing clearer, more streamlined guidance that reduces unnecessary administrative burden. Doing so would improve efficiency, encourage lender participation, and help small businesses access capital more quickly.
- The 7a program remains one of the most effective tools available for helping small businesses access capital. From my perspective as an SBA Program Manager at a community bank, one of the biggest challenges is the complexity and frequent changes in SBA guidance and procedures. Lenders want to do the right thing and serve small business customers efficiently, however interpreting new rules and ensuring consistency can be difficult. Greater clarity and consistent guidance would help lenders make decisions more confidently and deliver a better borrower experience.
I also believe the SBA should continue seeking input from lenders of all sizes. Community banks often provide a unique perspective because we’re working closely with local businesses and seeing firsthand how program changes impact borrowers. Ensuring those voices are heard can help create practical solutions that strengthen the program for everyone.
As someone who has benefited from NAGGL’s training, resources, and advocacy throughout my career, I’ve seen the value of bringing lenders together to identify challenges and work toward solutions. The most successful improvements to the 7a program come when the SBA and lending community collaborate to make the program more efficient, consistent, and accessible while maintaining its integrity.
- NAGGL’s top priority should continue to be to ensure that lenders continue to have a strong voice in shaping the future of SBA lending. As someone who manages our bank’s SBA program, I’ve relied on NAGGL for training, guidance, and feedback to challenging questions over the years. What I’ve come to appreciate most is that NAGGL does not just educate lenders, it advocates for us. When changes occur within the SBA program, lenders need an organization that understands what those changes look like in practice and can communicate those impacts back to the SBA.
Community banks play an important role in serving small businesses, and we often see challenges and opportunities that may not be visible at a national level. I believe NAGGL’s most important responsibility is gathering those perspectives and using them to promote clarity, consistency, and efficiency within the 7(a) program.
Ultimately, when lenders are better supported and better represented, small business borrowers benefit as well. That’s why I believe advocacy on behalf of the lending community should remain NAGGL’s highest priority.
Caroline Taylor
Chief Lending Officer, SVP, Mechanics & Farmers Bank
About Caroline
Caroline Taylor is a senior financial services executive and the Chief Lending Officer at M&F Bank, where she leads the bank’s lending strategy and oversees commercial origination and the SBA line of business. With more than 25 years of experience in Small Business and SBA lending, she is known for building high performing, compliant lending organizations that deliver sustainable growth, operational efficiency, and strong portfolio performance. Her leadership is grounded in practical execution, regulatory fluency, and disciplined risk management.
Before joining M&F Bank, Caroline served as Senior Vice President and Head of SBA Lending at Regions Bank, where she led national SBA strategy, rebuilt and expanded production teams, and delivered significant year over year growth in lending volume and revenue while maintaining exceptional credit quality. She is widely recognized as a subject matter expert in SBA lending, regulatory compliance, and risk management, and is a frequent speaker for national industry organizations.
Previously, Caroline held multiple senior leadership roles at Capital One, including National Head of SBA Lending and Director of Small Business Credit Underwriting. In these roles, she established and scaled SBA platforms, launched innovative franchise and small dollar lending initiatives, and oversaw portfolio growth exceeding $300 million.
Caroline serves as an Executive Board Member of NAGGL, is an active member of the Technical Committee, and co chairs the Disaster Relief Committee. She previously served on the Board of Directors for the North Carolina Bankers Association. She holds a Bachelor of Arts in Political Science from North Carolina State University and has completed advanced leadership and commercial credit programs through Wells Fargo and the University of Virginia Darden School of Business. She remains deeply committed to community involvement and mentorship.
Answers to Questions
- If I could make one change to the SBA 7(a) program, it would be to establish a more disciplined, technology-enabled process for developing, communicating, and implementing policy changes. SBA should provide clearer guidance, sufficient lead time, standardized training, and practical implementation resources whenever material rules, SOPs, or procedures change.
As a Chief Lending Officer who has led multiple SBA lending platforms, grown portfolios, and worked alongside experienced SBA professionals, I understand that lenders can adapt to change. The challenge is not change itself, it is frequent change without consistent interpretation, adequate preparation, or systems that support efficient execution. Recent updates to underwriting, servicing, and eligibility requirements illustrate the operational burden lenders face when guidance evolves quickly.
A modern SBA platform should use technology and AI to centralize guidance, flag policy impacts, improve workflow consistency, and support compliance monitoring. However, technology must reinforce, not replace the expertise and judgment of qualified SBA lenders. A more predictable, transparent implementation model would reduce errors, improve lender confidence, protect program integrity, and allow lenders to focus more of their energy on responsibly serving small businesses.
- SBA should focus on strengthening program oversight and execution while preserving the 7(a) program’s ability to deliver timely, responsible capital to small businesses. The greatest weaknesses are often inconsistency in policy interpretation, uneven lender knowledge and experience, and insufficient controls to identify and address poor practices before they harm borrowers, lenders, or the program’s reputation.
SBA should modernize its processes by appropriately leveraging technology and AI to improve application review, detect risk patterns, identify potential fraud, and streamline routine compliance work. These tools should enhance, not replace, sound underwriting judgment, due process, and the integrity of the program.
Equally important, SBA must ensure all participating lenders are thoroughly trained on program requirements, eligibility, underwriting, servicing, liquidation, and documentation standards. Clear guidance, accessible training, consistent oversight, and quality audit reviews are essential. Lenders that repeatedly fail to meet standards or misuse the program should be held accountable so that a few bad actors do not undermine the many lenders committed to serving small businesses responsibly.
- NAGGL’s top priority should be continuing to protect and strengthen the long-term integrity, accessibility, and predictability of the SBA 7(a) program. That means serving as the unified, credible voice of lenders while advocating for policies that expand responsible access to capital for small businesses without creating unnecessary complexity, cost, or uncertainty for participating lenders.
In my view, NAGGL should focus on three connected areas: stable program funding and guarantee authority; clear, practical, and consistently applied SBA guidance; and preservation of lender flexibility to make sound credit decisions within a strong risk-management framework. Recent policy changes underscore how important it is for NAGGL to engage early, provide operational feedback, and help ensure implementation is workable for lenders and beneficial to borrowers.
Having served on the board for six years, I believe NAGGL is at its best when it brings together diverse lender perspectives, translates front-line experience into thoughtful advocacy, and protects the 7(a) program as a reliable tool for small-business growth.
Associate Member Category (1 Seat Open, 6 Nominees)

Mark Ahern
President, AMP Business Valuations
Charles Bailey
President, The Bailey Group
Shay Kleinschmidt
Executive Vice President of Business Development, FranFund
About Mark
Mark Ahern is the founder and principal of AMP Business Valuations, a boutique business valuation and financial consulting firm he built from the ground up into a leading small business valuation provider across the Midwest and Rocky Mountain region. Based in Golden, Colorado, AMP serves SBA lenders, estate planning attorneys, M&A advisors, and CPAs. Mark holds an MBA from DePaul University along with three business valuation credentials: Certified Valuation Analyst (CVA), Accredited in Business Valuation (ABV), and Master Analyst in Financial Forensics (MAFF).
Before founding AMP, Mark spent nearly a decade in commercial banking and finance, including roles at Wells Fargo Commercial Banking and GE Capital, following credit and leadership training programs at First Midwest Bank and First American Bank. That lender’s perspective informs his approach to valuation today, particularly in SBA engagements governed by SOP 50 10, where he currently serves as Secretary of NAGGL Region VIII and participates in SBA regional liaison committee work.
A lifelong advocate for small business, Mark believes sound financial diligence is foundational to healthy lending relationships and thriving local economies. Ethics and professional integrity are not incidental to his practice, they are its foundation.
Mark would welcome the opportunity to bring this perspective to the NAGGL Board of Directors.
Answers to Questions
- The SBA has taken appropriate steps with SOP 50 10 8.1 to increase due diligence requirements for larger transactions. After 15 years working closely with small business owners as a lender, consultant, and appraiser, it’s clear to me that we cannot shortcut proper due diligence if the goal is successful borrowers and strong loan performance over the long run. Buyers utilizing the business acquisition program are taking on significant financial risk, and we ought to ensure the cash flow numbers used in lending decisions are properly validated.
I propose extending a review mechanism to business valuation for larger or higher-risk transactions as well. Business valuation has no equivalent to the FIRREA framework that governs real estate appraisals, meaning there’s nothing in place to ensure independence, adherence to professional standards, or overall defensibility of the work product. Without that structure, repeat referrals become the currency that matters most, and that often puts the appraiser in an ethical bind to produce a defensible number or produce the number that keeps the referrals coming. SBA should close that gap the same way it did for real estate. - If I had to name a structural weakness in the 7(a) program, it’s that the risk embedded in a transaction doesn’t always get identified, validated, and reflected in how the deal is structured. Two examples stand out to me.
First, the cash flow figures underwriting these loans come from a valuation provider the lender selected directly, with no outside review of the finished work. SOP 50 10 8.1 raised due diligence requirements for larger deals, but due diligence is only as strong as its inputs. Mortgage lending solved a similar problem years ago by requiring independent review so the person valuing the collateral isn’t beholden to the party who hired them. Business valuation has no equivalent yet, and that’s less a reflection on practitioners than on a system that doesn’t ask for an outside check.
Second, real risk factors like customer concentration often get absorbed into a historical cash flow number instead of being addressed in deal terms. A business earning a large share of revenue from one or two customers carries real post-closing risk. SBA should consider requiring additional seller carry, or a longer standby period, when concentration exceeds a defined threshold, so risk shows up in the structure and not just the numbers.
- I’d like NAGGL to prioritize transparency and open lines of communication with its membership, particularly when it comes to major regulatory developments. That relationship should mean that when something as significant as this recent SOP update rolls out, members hear about it directly from NAGGL as part of that commitment, not through a separate paywall.
Charging $405 for a webinar to understand a mandatory regulatory change doesn’t align with that relationship. Members are already funding the association’s role as our voice in Washington; we shouldn’t also be charged to hear from that same association when the rules we operate under change in a meaningful way.
If elected to the board, I’d advocate for enhancing NAGGL’s value to members in alignment with its mission.
About Charles
My name is Charles Bailey, and I am President and owner of The Bailey Group based in Tampa, FL. Our company is a leading provider of life insurance used as collateral for small business owners seeking capital through commercial lenders offering SBA loans. I started my company after having seven years of insurance industry experience with two global companies, with a realization of the need for a national firm that could offer an expedited process for the needs of an SBA borrower. The Bailey Group is a 22-year member of NAGGL and has supported the association and its goals while also sponsoring and exhibiting at both NAGGL conferences annually since 2003. I have served on the Board of Directors of NAGGL since 2018, and I am excited to further support NAGGL’s objectives in strengthening our commitment to the small business owners creating jobs in communities across the U.S.
Answers to Questions
- Legislation should be proposed to provide the SBA Administrator the ability to increase the authorization level in times where SBA loan demand has exceeded capacity. This flexibility will help ensure continuity and adequate program funding in times when 7(a) loans are needed the most. Increased utilization of the program in the past has exceeded the authorization limit, resulting in emergency action by Congress. With the Administrator flexibility, while the program operates at zero subsidy, the 7a lending can operate without the risk of shutdown.
- The SBA should further its focus on improving the lender oversight process to proactively identify risks in lending activity or portfolio trends that would threaten the viability of the program. Data, including SBA’s analysis, should be readily available to lenders to indicate any issues that are developing by industry, geography, or other risk factors. Nothing is more important than having the appropriate guardrails in place that will best secure the viability of the program long-term.
- NAGGL’s first priority should be to continue acting as liaison between the lending community, Congress, and the SBA. Through the education of lenders and Congress on the proper utilization of the 7(a) program, NAGGL is able to help craft a program that provides the necessary permanent financing for small businesses across the country. As a Board member, I will work to bring the ideas and concerns of the Lenders and Associates to the leadership body and ensure the actions of the Association continue to represent the best interest of all parties including the small business customers, lenders, and the government.
About Shay
As Executive Vice President of Business Development at FranFund, Shay Kleinschmidt leads strategic growth, partnerships, and market expansion, with a focus on helping entrepreneurs and small businesses access the capital and resources needed to grow.
Since joining FranFund in 2012, Shay has built deep experience across the SBA lending and franchising communities, working closely with lenders, referral partners, and business owners to navigate complex funding needs and an evolving lending environment.
Shay is actively involved with NAGGL and currently serves on the Associate Member Committee, Policy Committee, and Region VI Committee. She also serves on the IFA Supplier Forum Advisory Board and the Titus Center for Franchising Advisory Board at Palm Beach Atlantic University.
She was recognized as the Coleman Report’s 2019 Emerging SBA Lender of the Year and 2026 SBA Franchise Lender Professional of the Year was named one of the Top 50 Women Leaders in Finance in both 2024 and 2025.
Shay would bring to the NAGGL Board a collaborative, relationship-driven perspective, a strong voice for associate members, and a commitment to education, industry engagement, and strengthening the SBA lending community.
Answers to Questions
- If I could make one change to the 7(a) program, I would increase the maximum loan amount from $5 million to $10 million. The cost of starting, acquiring, expanding, and operating a small business has increased significantly, yet the 7(a) maximum has not kept pace with inflation or the economic realities facing today’s entrepreneurs. Rising real estate, construction, equipment, labor, inventory, and acquisition costs mean that otherwise eligible small businesses can outgrow the program simply because their capital needs exceed the current limit. Increasing the maximum to $10 million would modernize the program and allow it to remain relevant to the businesses it was designed to support. It would also give lenders greater ability to structure complete financing solutions rather than requiring borrowers to seek additional, potentially more costly or complicated sources of capital. Importantly, increasing the cap would not mean lowering SBA’s credit or underwriting standards. Borrowers would still need to demonstrate eligibility, creditworthiness, and the ability to repay. If we want the 7(a) program to continue supporting small business growth nationwide, its lending capacity should evolve alongside the economic environment in which those businesses operate.
- I believe SBA should focus on four areas: improving efficiency, increasing transparency, expanding access, and recognizing the value of responsible industry partners.
First, the 7(a) Small program should be more streamlined and risk-based. These borrowers often need the most support, yet the process can be disproportionately complex relative to loan size, discouraging lender participation.
Second, SBA should improve Franchise Directory transparency by publishing brands that have been reviewed and determined ineligible. Lenders and agents should not have to repeatedly contact SBA or discover eligibility issues after a transaction is underway.
Third, I support restoring eligibility for Lawful Permanent Residents. Excluding otherwise qualified business owners who are legally residing and building businesses in the U.S. unnecessarily restricts access to capital.
Finally, SBA should foster a more collaborative approach toward ethical, compliant agents. Agents who understand and follow SBA requirements can be an incredible resource to borrowers and lenders, providing education, packaging expertise, and guidance that helps transactions reach lenders better prepared. Rather than viewing agents primarily through a risk lens, SBA should recognize the value responsible agents bring while maintaining strong accountability for bad actors.
Improving efficiency, transparency, access, and collaboration would strengthen the 7(a) program for everyone involved. - I would recommend that NAGGL make continued lender and agent participation in the 7(a) program a top priority, particularly by advocating for greater clarity and flexibility around permissible fees.
One example is the current “two-master” concern and the gray area surrounding whether a lender and an agent may each charge for distinct services that may fall under the same fee category, such as a packaging fee, even when those services are performed independently and at different stages of the process.
SBA is right to focus on protecting applicants from excessive or duplicative fees, but the policy should also recognize the legitimate and distinct value and cost of services provided by lenders and agents.
This is especially important in the 7(a) Small Loan program, where borrowers often need the most guidance, education, and hands-on support, yet lender participation remains limited.
A clearer, more balanced fee framework could encourage broader participation, expand borrower access to knowledgeable support, and strengthen the program overall. Protecting applicants and sustaining the professionals who serve them should not be competing goals; the program works best when both are addressed.
Rachel Russell
Lender Services Director, B:Side Capital
Andrew "Andy" Starfield
Managing Partner, Broad Street Financial
Omri Yacubovich
CEO, Lama AI
About Rachel
Rachel Russell is a passionate and experienced advocate for small businesses, currently running for a seat on the NAGGL Board of Directors. Rachel serves as a key leader at B:Side Capital, a Lender Service Provider (LSP) and Certified Development Company (CDC). B:Side Capital’s mission focuses on fostering economic opportunity by delivering innovative, high-quality SBA lending services Since 2010, Rachel has dedicated her career to facilitating responsible small business financing. Over the past 16 years, she and her team have facilitated over 1,000 7(a) loans, directly supporting over $832 Million in loans.
Rachel brings a distinctive and valuable perspective that would enrich the NAGGL Board. She is deeply attuned to the challenges and opportunities facing lenders committed to both fiscal responsibility and community impact. Serving over 60 banking partners, many being community banks, her insights into the unique role that lenders play in the SBA ecosystem will help ensure all voices are well represented in national advocacy and policy discussions.
Rachel’s candidacy reflects her commitment to advancing SBA lending practices that promote access to responsible capital, and sustained economic growth for all small businesses.
Answers to Questions
- I would focus on enhancing lending opportunities for veterans. Veterans and their spouses deserve distinct program enhancements that not only provide fee relief for borrowers but also meaningfully incentivize lenders to originate 7(a) loans. I believe loans to veterans or their spouses should benefit from a higher SBA guarantee percentage, helping to reduce lender risk and promote greater access to capital.
Additionally, it is essential that the definition of “veteran-owned” be consistent across all SBA programs. For example, under the 504 program, spouses of veterans are not currently recognized as part of a veteran-owned business, a disparity that should be corrected. The process of verifying veteran status should also be streamlined, with the SBA assuming responsibility for status verification during compliance checks, rather than placing the burden of documentation on the borrower.
SBA has made positive improvements to this lending segment but more can be done.
- I believe the SBA can enhance its performance in customer service and response times for loans in liquidation. Currently, communication is often repetitive, wait times are lengthy, and there is little clarity about where a loan stands. Providing greater transparency and clearer guidance would be valuable, building confidence among lenders, especially those who do not navigate this process frequently.
- If the lending community and Congress move forward with doubling the maximum 7(a) loan size, it is essential to also re-evaluate other “maximum” thresholds within the SBA program. I would recommend that NAGGL lead an initiative to systematically review and update all SBA maximum thresholds to reflect inflation and current market conditions.
Examples of thresholds that merit reconsideration include: the litigation expense limits requiring SBA approval, the recoverable value threshold for collateral abandonment, the minimum construction contingency percentage, the $2,500 cap on packaging fees needing documentation, among others. A comprehensive reassessment would help ensure these limits remain current in today’s lending environment.
About Andy
Andy Starfield is Managing Partner of Broad Street Financial, a boutique financial planning firm focused on helping business owners protect, grow, and ultimately transition what they have built.
Andy began his career in SBA lending before entering financial services in 2009, giving him a practical understanding of the challenges business owners face when balancing growth, risk, liquidity, and long-term planning. Today, he specializes in risk management, wealth planning, and business-owner strategies, with a particular focus on life insurance, disability protection, succession planning, and estate planning.
Andy also leads a niche national practice supporting SBA lenders and borrowers with the life and disability insurance requirements tied to business loans. His team is known for helping lenders and borrowers move quickly, clearly, and compliantly through the insurance process.
In addition to his role at Broad Street, Andy serves as a committee chair for the National Association of Government Guaranteed Lenders (NAGGL) and the MassMutual Advisors Association. He holds the Chartered Financial Consultant® and Business Succession Planner® designations from The American College of Financial Services.
Andy lives in Bryn Mawr, PA with his wife, Amit, and their two sons, Eli and Isaac.
Answers to Questions
- I would increase the 7(a) loan limit to better reflect today’s business valuations, acquisition costs, and capital needs. The program has to evolve with the businesses it is designed to serve, and a higher limit would allow it to remain relevant for a broader range of growing small businesses.
- I believe SBA should focus on greater consistency, clarity, and predictability. When rules or interpretations change frequently — or are applied differently — it creates uncertainty for lenders and borrowers and can ultimately slow access to capital. A more predictable program would benefit everyone involved.
- NAGGL’s top priority should be advocating for greater stability and predictability in the 7(a) program. The industry can handle higher standards and reasonable changes, but lenders need enough clarity and lead time to implement them effectively. NAGGL should push for changes to be well-vetted, clearly communicated, and implemented in a way that minimizes disruption to lenders and small businesses.
About Shay
Omri Yacubovich is the Co-Founder and CEO of Lama AI, the first AI-Native commercial loan origination platform focused on SBA and SMB Lending. Omri brings a unique combination of banking, financial, and AI driven industry experience.
He began his career with a strong foundation in accounting and financial services, which then led him to lead growth and innovation initiatives within the largest bank out of Israel, including founding, building and scaling a neobank.
Prior to Lama AI, Omri was an executive at an insurtech company focused on leveraging big data and AI to unlock new opportunities in the SMB insurance market. There, he worked on applying advanced data capabilities to improve underwriting, risk assessment, and customer acquisition in complex, underserved segments.
Omri has spent his career at the intersection of financial services, data, and growth, consistently identifying large, overlooked market opportunities and building technology driven solutions to capture them. At Lama AI, he is focused on redefining how financial institutions serve SMBs by transforming lending infrastructure through responsible AI usage.
Answers to Questions
- As SBA replaces E-Tran, I would ensure the new infrastructure is designed to work inside lenders’ existing systems, and not become another thing that lenders need to switch to, tracking statuses in multiple systems. SBA should define the validations and controls, while allowing trusted lender platforms to execute them securely within the lending workflow.
- The program relies too much on repetitive processes and strict rules to create trust, even when a lender has demonstrated strong controls and performance. SBA should use actual lender and portfolio performance to allow more room for judgment while making lenders more accountable, determine where oversight belongs, giving proven lenders greater operating flexibility while concentrating scrutiny where the program is truly at risk, and provide better clarity on requirements. The goal is to increase access to capital for small businesses, and not to make it harder for them.
- NAGGL’s top priority should be ensuring that the next generation of the 7(a) program is designed with lenders, not just for lenders. As SBA modernizes its technology and oversight, NAGGL should ensure the industry’s experience shapes the standards for interoperability, responsible AI, lender accountability, and the operating flexibility needed to responsibly expand access to capital.